Changes are coming to the Victorian property industry. There is widespread community frustration at the housing status quo. While there are good arguments that the housing crisis is a symptom of inequality, rather than an underlying lack of property, the government is using public outrage to push through new laws which will greatly impact the way property is bought and sold in Victoria. There are some excellent amendments in the works, and there are others that are a bit baffling. We’ll see what the final outcome of the Consumer Legislation Amendment Bill 2026 (Vic) is once it passes both Houses.
Agents will be required to publish a reserve price a week before the auction, to stop wasting everyone’s time.
Underquoting is our national sport. Any price shown on an auction campaign is at least 10% under the actual price. In high demand locations, this may be closer to 20%. I rent in Fitzroy and see this story every Saturday:
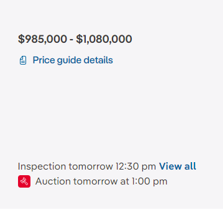
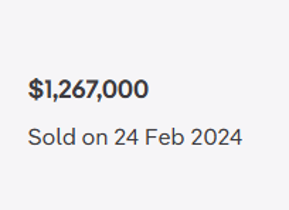
If you doubt me, try making a pre-auction offer within the range. Last year a client asked me to call an agent and put in an offer 10% above the top of the range, and the agent laughed and said ”no, I’ve spoken to your client about this before, there’s no way the property is being sold for that low”. While such activity is supposedly illegal, the rules are rarely enforced.
Once the new laws are passed, agents must publish the price the Vendor will actually accept 7 days before the auction. Potential bidders misled by false price guides can then do something more productive with their weekend.
Agents will no longer be able to withhold their commission and expenses from the Deposit, and Section 27 will be abolished
Agents will often push for an early Deposit release (“Section 27”) so they can get paid. Going forward, they will no longer be able to withhold an amount equal to their commission and marketing costs. I expect there will be much less agent pressure to have Purchasers sign a Section 27. This change makes sense and I support it.
What makes less sense is abolishing Section 27 of the Sale of Land Act, which is well understood by practitioners with plenty of case law clarifying it. Deposit releases will be allowed by Special Condition, but this will add uncertainty and create risks for both buyers and sellers unnecessarily. I don’t always agree with the REIV, however their assertion that it will make auctions hazardous for buyers is spot on – buyers may be forced to accept the deposit release terms that sellers dictate.
Sections 32 Vendor Statements to be made available 14 days prior to sale
Currently, buyers must be given a Section 32 Vendor’s Statement before signing the Contract. The proposed change will require the Vendor Statement to be made available upon request 14 days prior to the Contract being signed, or the Auction date (depending). Buyers and sellers, despite reaching an agreement, would have to wait for a period before the Contract could be signed. This is a change that is perhaps the most perplexing.
Fortunately, the Legislative Council has made amendments to this section to create an off-market exemption, among other amendments. Watch this space.
If you’re buying, selling, or anything in between, email Jack at jack.nevile@nevile.com.au
An NDA (or non-disclosure deed) is a useful tool, but it is not a guarantee of secrecy. It creates enforceable obligations, yet enforcing them still requires you to take action and pay legal costs. For an early-stage business, proving loss after a breach can be difficult. How you define “confidential information” and how you handle disclosures often matters more than the document itself.
Why founders reach for an NDA – and where it falls short
Founders commonly want an NDA when they start engaging staff and contractors — social media managers, designers, photographers, videographers and content creators — who will see sensitive material. That instinct is sound. A well-drafted non-disclosure deed can limit, if not obviate, the risk of confidential business information reaching competitors.
But an NDA has real limitations, and understanding them before you disclose anything is what protects the business.
First, a deed only deters. In reality, a breach still requires you to take enforcement action, and to bear legal costs to do so. The legal obligation exists, but the protective value is inherently limited once commercially sensitive information is released to a third party.
Second, once information enters the public domain, it can be difficult or impossible to restore its confidential character. It can also be hard to prove how the information became public, or who was responsible for it.
Third, damages may be an inadequate remedy. Even with a successful claim, monetary compensation depends on the breaching party’s ability to pay.
How this arose in a real matter we acted in
We acted for the founder of an early-stage technology platform who wanted contractors and marketing personnel to sign an NDA before the product launch. We prepared a Non-Disclosure Deed and a detailed letter of advice on its practical use.
Two issues stood out.
The definition of “confidential information” had to be precise. Casting the net too wide is a genuine risk: if the clause tries to capture everything, a court may invalidate the specification of confidential information entirely. We therefore identified as precisely as possible the categories to be protected — business plans, financials, software, algorithms, branding, marketing strategy, analytics and unpublished content — rather than relying on a vague catch-all.
Proving loss was the second issue. Damages claim may require the disclosing party to prove lost profit. A new start-up may lack the historical records to do so — and may have no profit yet. We recommended obtaining feasibility studies or financial projections early, as these can materially affect what is recoverable if the deed is later breached.
Practical guidance for businesses using an NDA
- Define confidential information precisely. Over-breadth can undermine the whole clause.
- Disclose only what you need to. A general summary, without core details, is often enough until the recipient genuinely needs more.
- Manage the disclosure itself. Mark documents “CONFIDENTIAL”, and consider watermarking with timestamps, version details and the identity of who accessed them.
- Address the “I already knew that” defence. Before disclosing, discuss what the recipient already knows or is working on.
- Keep records to support future loss. Feasibility work and projections improve your position if you ever need to claim.
It is also worth remembering the commercial reality: some information is best protected by not disclosing it at all, rather than by relying on a contract to unwind a disclosure after the fact.
Quick Answer
An NDA (non-disclosure deed) creates enforceable confidentiality obligations, but it does not guarantee secrecy. Enforcement still requires action and legal costs, and once information is public its confidentiality may be irreversible. For start-ups, proving financial loss is often difficult. Define confidential information precisely, limit disclosure, keep records, and execute the deed correctly.
FAQs
Is an NDA legally enforceable in Australia? Yes. A properly drafted and correctly executed NDA or non-disclosure deed is enforceable. However, enforcement requires you to take action and bear legal costs, and remedies such as damages depend on proving loss and the other party’s capacity to pay.
Should the definition of “confidential information” be as broad as possible? No. If the definition is too broad, a court may invalidate the clause specifying confidential information altogether. It is better to identify the categories you genuinely need to protect.
About the Author
Meng Cheong – Partner
Meng was the partner responsible for this matter and advises on commercial agreements, confidentiality and non-disclosure arrangements, and start-up and technology transactions. He settled the non-disclosure deed and letter of advice and provided the strategic advice on the practical limits of confidentiality protection.
Anna-Nikol Tanti – Lawyer
Anna-Nikol assisted with the conduct of the matter, including preparing the draft non-disclosure deed and correspondence, undertaking company searches and liaising with the client on execution requirements.
This article provides general information only and is not legal advice. It is based on a matter we handled, with identifying details generalised for confidentiality. You should obtain advice tailored to your circumstances before acting.
A director who resigns does not automatically stop being a guarantor of the company’s debts.
A personal guarantee to a bank survives your resignation, your share transfer and even a settlement deed.
The bank is not a party to your exit agreement and is not bound by it.
Until the lender formally releases you, you remain personally liable — often for years.
The legal issue: resignation and release are two different things
Resigning as a director is a step you can take unilaterally. Being released from a personal guarantee is not. A guarantee is a separate contract between you and the lender. The company’s internal reshuffle does not touch it.
This distinction routinely surprises departing business owners. They negotiate an exit, sign the transfer of their shares, lodge the ASIC forms — and then discover they are still on the hook to the bank. The remaining owner may promise to “attempt” to remove them, but an attempt is not a release.
Two practical mechanisms exist to achieve an actual release: the remaining party refinances the loan in their own name, or the lender agrees in writing to discharge the departing guarantor. Both depend on the lender’s assessment of the company and the remaining guarantor — not on what the departing party wants.
How this arose in a matter we acted on
In a shareholder dispute we handled through 2024 and 2025, our client was a 50% shareholder and co-director of a company. He and the other owner had each given the company’s bank personal guarantees over loans that, by early 2025, totalled around $100,000, not due to be repaid until 2029.
The two directors could not work with each other anymore. The parties negotiated our client’s exit: he would resign as director, transfer his 50% shareholding, keep certain equipment and intellectual property, and receive a cash sum. The sticking point was the personal guarantee.
Correspondence with the bank confirmed the practical reality — the bank would only assess removing the guarantee once the departing director had resigned, the shareholding was regularised, and up-to-date financials supported the remaining guarantor alone.
When negotiations stalled, our client commenced an oppression proceeding in the Supreme Court of Victoria (Commercial Court, Corporations List), which was referred to the Court’s Oppression Proceeding Program. We successfully negotiated for our client’s personal guarantee to be released. The matter was resolved and the proceeding came to an end.
Practical guidance for anyone leaving a jointly owned company
- Treat the guarantee as the central term, not an afterthought. Your resignation is easy; your release is the hard part.
- Insist on an outcome, not an “attempt.” A clause requiring “reasonable endeavours” leaves you exposed if the bank says no.
- Get an indemnity in the meantime. If release cannot happen immediately, require the remaining owner to indemnify you against bank claims until it does — and consider security for that indemnity.
- Confirm the lender’s actual requirements early. Ask the bank what it needs (resignation, share position, financials) before you finalise terms, so the deed reflects reality.
- Watch the timing. Releasing a guarantee can take weeks and depends on the remaining party’s creditworthiness, which you cannot control.
Personal guarantees are governed by ordinary contract principles, while the oppression remedy for shareholders sits in section 232 and 233 of the Corporations Act 2001 (Cth). Victorian oppression proceedings are managed under the Supreme Court’s Practice Note SC CC 8 – Oppressive Conduct in the Affairs of a Company. General guidance on directors’ obligations is available from ASIC.
Quick Answer
Resigning as a director does not release you from a personal guarantee you gave to the company’s bank. The guarantee is a separate contract with the lender, who is not bound by your exit deed. Until the bank agrees in writing to release you — or the debt is refinanced — you remain personally liable, sometimes for years. Negotiate a real release and an interim indemnity.
FAQs
Does resigning as a director cancel my personal guarantee? No. Resignation ends your role in the company but has no effect on a guarantee you gave the bank. The guarantee continues until the lender formally releases you or the loan is refinanced.
Can the other shareholder force the bank to remove me? No. Only the lender can release you. The remaining owner can apply for a refinance or discharge, but the bank decides, based on its own assessment of the company and the remaining guarantor.
What protection can I get if release is not immediate? Ask for a written indemnity from the remaining party covering any bank claim until you are released, ideally supported by security, plus a clear obligation on them to pursue the release actively.
Is court the only way to resolve a 50/50 shareholder deadlock? No. Court is often the last resort. An oppression proceeding under the Corporations Act can be a lever, but many disputes resolve by negotiated deed — sometimes after proceedings are issued, then dismissed by consent.
About the Author
Meng Cheong – Partner Meng Cheong was the partner responsible for this matter and advises on shareholder disputes, business separations and commercial negotiations. He led the negotiation of the exit terms, the guarantee and indemnity provisions, and the conduct of the oppression proceeding in the Supreme Court of Victoria.
Anna-Nikol Tanti – Lawyer
Anna-Nikol Tanti assisted Meng Cheong throughout the matter, including taking the client’s instructions, managing correspondence with the other side, preparing the amended deed for circulation, and coordinating service of the court documents.
This article provides general information only and is not legal advice. Every matter turns on its own facts. You should obtain advice specific to your circumstances before acting.
Selling a business is not just about price. How the sale is structured — as an asset sale or a share sale — affects tax, risk and how much administrative work each side must do.
An asset sale is often preferred by buyers, but it can be far more cumbersome for the seller. A share sale can be simpler to implement but usually requires deeper due diligence. Tax consequences frequently determine which structure is chosen. The right answer depends on the specific business, not a general rule.
The two structures, in short
In an asset sale, the buyer purchases the individual assets of the business — plant, stock, intellectual property, goodwill and the benefit of contracts. Each contract must be assigned or novated, and assets such as vehicles must be individually transferred.
In a share sale, the buyer acquires the company itself. Contracts, licences and employees generally remain in place because the legal entity does not change. That convenience comes at the price of inheriting the company’s history — hence more searching due diligence.
How the issue arose in a business we acted on
A few years ago, we acted for the vendor in the sale of an established pest control business to an international acquirer. The initial plan was an asset sale.
We identified real practical burdens with that structure. Thousands of individual customer contracts would need to be assigned. Approximately 85 motor vehicles required transfer, including roadworthy certificates, re-registration and stamp duty. There was also the question of transferring staff.
We then raised a tax concern that mattered more than the paperwork. There was a possibility the Australian Taxation Office might treat an earlier event as a capital gains tax event affecting the vendor. That risk did not affect the buyer, but it could significantly affect our client. On that basis, all parties agreed it was prudent to seek a private tax ruling before locking in the structure, and to place the question of structure on hold until the ruling issued.
To keep the deal moving while that was resolved, we suggested the buyer provide a letter of intent that expressly left open whether the sale would proceed as an asset or share sale, preserve exclusivity, and pay a fully refundable deposit held in escrow.
Managing risk when an asset sale proceeds
The transaction ultimately completed by asset sale. Two features of the structure did the heavy lifting on risk.
First, instead of a warranty and indemnity insurance policy, the parties used a holdback: assets exceeding a set value were left in, together with a contingency payment, to stand as security against contingent tax, regulatory or employment liabilities for a period after completion.
Second, because the vendor company was to be deregistered, we prepared a deed of assignment so the vendor’s right to receive the withholding amount could be assigned to an individual already party to the agreement. We flagged an important limit: an assignment can transfer the benefit of a contract, but it cannot shift the vendor’s obligations — the company remained responsible for performing them.
Where obligations needed to move, we used a deed of novation with the incoming party assuming liabilities and indemnifying the outgoing party, and a release negotiated so the company could ultimately be deregistered. Because the agreement did not permit assignment before completion without consent, we built the purchaser’s consent into the deed itself.
What sellers and buyers should consider
- Decide structure early, but keep it open if tax is uncertain. A private ruling can be worth waiting for.
- Count the moving parts. Thousands of contracts and dozens of vehicles turn an asset sale into a logistical project.
- Assignment is not novation. Assignment moves benefits; novation is needed to move obligations and release the original party.
- Check the contract’s consent rules. Many agreements prohibit assignment before completion without written consent.
- Consider a holdback as an alternative to warranty insurance for contingent liabilities.
Quick answer
Whether to sell a business by asset sale or share sale depends on tax, risk and administrative burden. Asset sales suit buyers but require every contract, vehicle and employee to be transferred individually. Share sales are simpler to implement but demand deeper due diligence. Where a capital gains tax event may exist, a private ATO ruling can decide the structure.
FAQs
What is the difference between an asset sale and a share sale? An asset sale transfers individual assets — plant, stock, goodwill and contracts. A share sale transfers ownership of the company itself, so contracts and staff generally stay in place. Each has different tax and risk consequences.
Why do asset sales create more work? Every contract must be assigned or novated, and assets such as vehicles must be transferred individually with registration and stamp duty.
What is a holdback in a business sale? A holdback retains part of the price or assets after completion as security against contingent liabilities such as tax or employment claims, sometimes used instead of warranty and indemnity insurance.
About the authors
Peter Nevile – Peter was the Principal lawyer responsible for this matter and led the negotiation of the transaction with an international acquirer. He advises on business sales, transaction structuring and commercial agreements.
Meng Cheong – Meng was the lawyer who assisted throughout, including preparing the sale agreement schedules and drafting the deeds of assignment and novation that allowed the vendor’s rights to be transferred and the company ultimately released.
This article provides general information only and is not legal advice. It is based on our experience of a particular matter, with identifying details omitted or generalised. You should obtain specific advice before acting on any matter discussed here.
A note on scope: this article draws on the facts of the matter and general transactional practice. It does not analyse how a court would decide any issue.
The Federal Government has, fortunately, reversed its proposed changes affecting testamentary trusts. Following significant industry concern, testamentary trusts have been exempted from the proposed 30% minimum tax on trusts.
This is welcome news, as testamentary trusts remain one of the most effective estate planning tools available.
A testamentary trust is a trust established under a person’s will. Unlike a discretionary family trust created during a person’s lifetime, a testamentary trust only comes into existence upon the will-maker’s death.
Through a testamentary trust, you can direct that all or part of your estate be held on trust for one or more beneficiaries. Depending on the terms of your will, the trust may be controlled by that beneficiary or by an independent trustee or even jointly.
One of the key advantages is that beneficiaries can enjoy the benefit of the inherited assets without necessarily owning them personally. This can provide valuable protection in a range of circumstances, including where a beneficiary:
- is financially inexperienced or prone to overspending;
- has a disability or requires ongoing assistance;
- is exposed to claims from creditors; or
- may face family law or other third-party claims in the future.
In addition to these asset protection benefits, testamentary trusts can also provide significant taxation advantages for beneficiaries, making them a highly flexible and effective estate planning strategy.
If you would like to discuss whether a testamentary trust is appropriate for your circumstances, or how it may benefit your intended beneficiaries, please contact Tracy Collins, our Accredited Wills and Estates Specialist or Anna Nikol Tanti.
Email: Tracy.collins@nevile.com.au
Ph: 03 9664 4700
Outdated deeds, missing variations and non-compliant distributions are exposing trustees and beneficiaries to serious tax and legal risk
By Tracy Collins | Accredited Specialist, Wills & Estates | Special Counsel, Nevile & Co. Lawyers
Discretionary trusts have been the workhorse of Australian family and business structuring for half a century. They are flexible, they distribute income tax-effectively between beneficiaries, and they offer a real measure of asset protection. But a trust is only as good as the document that governs it – and for an enormous number of trusts established in the 1970s, 1980s and 1990s, that document has not kept pace with the law, with the family it was built around, or even with itself.
In our practice, when we are asked to review a long-standing family trust, it is common to find that the client has not seen the original trust deed in years, is unaware of amendments made along the way, and has been relying on their accountant to prepare annual distribution resolutions based on assumptions about the trust terms rather than the deed itself. Individually, each of these gaps is a risk. Together, they can be the difference between an effective, tax-efficient structure and a trust that triggers a six-figure tax assessment, a family dispute, or both.
Most Important: Find the Complete Document Set
A discretionary trust is not a single document. It is the original deed, plus every deed of variation, deed of amendment, deed of appointment or removal of trustee, deed of appointment of appointor, and any deed extending the vesting date that has been executed since. We regularly see trusts where:
- The original deed cannot be located at all, and the trust has been operating for decades on the basis of a photocopy, a draft, or institutional memory.
- Variations were prepared by an accountant or adviser but never validly executed, stamped (where required) or retained.
- A variation was made without checking the variation power in the original deed, meaning the change may be void or voidable.
- Trustee or appointor changes were made informally – for example, by correspondence or minute – rather than by deed, leaving the formal trustee or appointor as someone who has since died, lost capacity, or has no ongoing connection with the family.
Before any distribution decision, restructuring step, succession plan or sale of trust assets is undertaken, the complete chain of documents needs to be assembled and reviewed by a lawyer, not simply assumed to be “the same as last year.” Where documents are missing, it may be possible to reconstruct the trust’s history or, in some cases, necessary to consider a court application or a deed of ratification or confirmation. The earlier this is identified, the more options are available and the lower the cost of fixing it.
Why So Many 1970s and 1980s Trusts Are Now a Problem
Discretionary trusts surged in popularity in Australia from the 1970s through the 1980s, driven by their income-splitting and asset protection benefits. Many of those original deeds are now 40 to 50 years old, and the standard precedents used at the time simply did not anticipate the issues that matter most today. Common defects we see in deeds of this vintage include:
No mechanism for death or incapacity of the controller
Most older deeds focus on the trustee and give little or no thought to the appointor (sometimes called the principal, guardian or other name) – the person who actually controls the trust by virtue of their power to appoint and remove trustees. Where a deed is silent on what happens if the appointor dies, loses capacity, or becomes bankrupt, control of the trust can pass unintentionally, become contested between family members, or fall into limbo with no one able to validly exercise the trustee’s powers. We have seen sibling disputes, blended family disputes and contested succession all stem from this single gap. A modern deed should clearly provide for a chain of successor appointors and a workable mechanism if an appointor loses capacity, including dovetailing with that person’s enduring power of attorney.
No effective trustee succession on death of an individual trustee
Where an individual (rather than a corporate trustee) holds office, an old deed often fails to specify clearly who steps in if that person dies or cannot act, particularly where the deed pre-dates current drafting practice. This can leave a trust effectively unable to be administered at exactly the moment – the death of the founder – when family members most need it to function smoothly.
No exclusion of foreign persons from the class of beneficiaries
This is, in our experience, the single most expensive defect in legacy trust deeds, and it is almost universal in deeds drafted before the mid-2010s. Older deeds typically define the beneficiary class extremely broadly – spouses of beneficiaries, all of their descendants, related entities, and so on – without any power for the trustee to permanently exclude foreign persons from that class. Because state revenue laws now look at who is capable of benefiting under the trust, not just who actually receives a distribution, a trust can be deemed a “foreign trust” simply because its potential beneficiary class includes someone who happens to be a foreign person, even if that person has never received and will never receive a cent.
The Tax Consequences of Getting It Wrong
The consequences of an outdated or non-compliant deed, or of distributions that do not strictly follow the trust terms, fall broadly into three categories.
1. Foreign person surcharges on land
If a discretionary trust holding Victorian (or other state) residential land is deemed a “foreign trust” because its beneficiary class is not validly restricted to exclude foreign persons, the trustee can become liable for foreign purchaser additional duty on acquisition (an extra 8% in Victoria, on top of standard duty) and absentee owner/foreign owner land tax surcharges every single year the land is held (currently up to 4% of the land’s taxable value per annum in Victoria, with similar surcharges in other states). These amounts are not trivial: on a $2 million investment property, a missed foreign-person exclusion can mean an additional $160,000 of duty on purchase and tens of thousands of dollars in extra land tax annually, often discovered only on a revenue office audit or at the point of sale, years after the exposure began, with interest and penalties added on top.
2. Trustee assessed at the top marginal rate
Under section 99A of the Income Tax Assessment Act 1936, if trust income is not validly and effectively distributed to a presently entitled beneficiary by the required date (30 June, with resolutions often needing to satisfy the ATO’s documented standards), the trustee can be assessed on that undistributed income at the top marginal rate, currently 47% including the Medicare levy, with no tax-free threshold. If a distribution resolution refers to a class of beneficiary that does not exist in the trust deed, names a beneficiary outside the defined class, or is made under a since-superseded version of the deed, the resolution may simply be invalid. The Commissioner can then treat the income as undistributed, exposing the trust to default assessment and reopening years that the family believed were settled.
3. Unintended capital gains tax and resettlement risk
Where a purported deed variation goes beyond the variation power actually contained in the original deed, the change may be regarded as creating a new trust for tax purposes – a “resettlement.” That can trigger a deemed disposal of trust assets for capital gains tax purposes and a fresh round of stamp duty, even though no assets were actually sold or transferred to anyone. This risk is heightened in older deeds where the variation power is narrow, ambiguous, or was simply not checked before a variation was made.
4. Family law and asset protection exposure
A trust that has lost a validly appointed controller, or whose control has drifted to the wrong person, is far more vulnerable in a family law property settlement or a creditor claim. Courts and litigants look closely at who really controls a trust; ambiguity in the chain of appointors and trustees creates uncertainty that works against the family the trust was meant to protect.
5. Disputes between beneficiaries and family members
Beyond tax, an unclear or outdated deed is fertile ground for disputes – over who should control the trust after a death, who was entitled to historical distributions, and whether a variation was ever validly made. These disputes are expensive to resolve and can do lasting damage to family relationships, often at the worst possible time, such as shortly after the death of a parent.
What a Proper Trust Review Involves
A thorough discretionary trust review should cover each of the following:
- Locating and verifying the original trust deed and every subsequent variation, appointment and removal document, confirming each was validly executed under the power available at the time.
- Confirming the current trustee and appointor (or principal/guardian) and checking that succession on death or incapacity is clearly and workably documented, including alignment with the controller’s will and enduring power of attorney.
- Reviewing the definition of beneficiary and confirming there is an effective, permanent power to exclude foreign persons, and exercising that power by deed where it exists but has not yet been used, particularly if the trust already holds or is going to hold real estate.
- Checking the vesting date and confirming the trust will not vest unintentionally, which carries its own significant tax consequences.
- Reviewing recent distribution resolutions against the actual terms of the deed, including the defined beneficiary class and any conditions on the trustee’s discretion.
- Considering whether the trust’s structure still matches the family’s current circumstances, including blended families, beneficiaries who have become non-residents, and business succession plans.
Our Recommendation
If your discretionary trust deed was prepared before 2015, has not been reviewed in the last three to five years, or you are not entirely sure where the original deed and all variations are currently held, now is the time to have it reviewed – before a property settlement, before the next round of land tax assessments, before a death in the family, and well before an ATO or State Revenue Office audit forces the issue. The cost of a proactive review is almost always a small fraction of the cost of unwinding a problem after the event.
Nevile & Co. Lawyers regularly assists trustees, appointors and their accountants to locate, review and, where necessary, vary discretionary trust deeds to ensure they reflect current law, current family circumstances, and the protections that a well-drafted modern deed should provide.
About the Author
Tracy Collins is an Accredited Specialist in Wills & Estates and Special Counsel at Nevile & Co. Lawyers. She advises on estate planning, testamentary and protective trusts, enduring powers of attorney, asset protection structuring including discretionary and family trusts, and the administration of deceased estates.
Contact Tracy Collins on (03) 9664 4700 or at nevileco@nevile.com.au to arrange a discretionary trust review.
This article is general information only, current as at June 2026, and does not constitute legal or tax advice. You should obtain advice specific to your circumstances before acting on any matter referred to in this article.
By Tracy Collins, Accredited Specialist (Wills & Estates), Special Counsel — Nevile & Co. Lawyers
If your discretionary (family) trust was set up in the 1970s, 80s or 90s, there’s a good chance the deed sitting in a drawer somewhere no longer matches the law — or your family.
Discretionary trusts were the go-to structure for decades because they’re flexible and tax-effective. But many older deeds were never updated, and the gaps they contain can be expensive.
Three questions every trustee should be able to answer
1. Can you put your hands on the original deed and every variation that’s been made since?
Trusts are often run for years on a photocopy, with informal trustee or controller changes that were never properly documented.
2. What happens if the person who controls the trust dies or loses capacity?
Many old deeds say nothing about succession of the appointor/principal — the person who really runs the trust. That silence has caused real family disputes.
3. Does your deed exclude “foreign persons” from the list of possible beneficiaries?
Almost all pre-2015 deeds don’t. If even one potential beneficiary (think: a child’s overseas spouse) falls into that category, your trust can be deemed a foreign trust.
Why this matters: the tax consequences
- Foreign purchaser duty & land tax surcharges — an extra 8% duty on purchase and up to 4% extra land tax every year on Victorian property if your trust is deemed foreign.
- Tax at 47% on undistributed income — under s99A, if a distribution resolution doesn’t strictly match the deed’s beneficiary class, the ATO can tax the trustee at the top marginal rate, with no tax-free threshold.
- Unintended CGT and stamp duty — a deed variation made outside the proper variation power can be treated as creating a new trust (“resettlement”), triggering CGT and duty on assets that were never actually sold.
- Family disputes and lost asset protection — unclear control of a trust is a magnet for disputes and weakens the very protection the trust was meant to provide.
These issues are usually discovered at the worst possible time — during an audit, a property sale, a death in the family, or a separation — when options are limited and costs are highest.
The fix is usually straightforward — if you act now
A trust review involves tracking down the full document history, checking who really controls the trust and what happens if they can’t, confirming foreign persons are properly excluded, and checking that past distributions actually match the deed. Most issues, caught early, can be fixed by deed for a modest cost. Caught late, they can cost tens or hundreds of thousands of dollars.
Take action today
If your trust deed is more than a few years old, don’t wait for a revenue office audit or a family crisis to find out it’s not fit for purpose.
Contact Tracy Collins at Nevile & Co. Lawyers for a discretionary trust review. 📞 (03) 9664 4700 ✉️ nevileco@nevile.com.au
This article is general information only, current as at June 2026, and is not legal or tax advice. Please obtain advice specific to your circumstances.
– Meng Cheong
Can You Be Bound by a Contract You Never Signed?
The short answer: maybe…
Long answer: it depends…
A lot of people assume a contract only becomes “real” once someone has scrawled their signature at the bottom, magically flipping the deal from ‘just chatting’ to ‘legally binding’. But that’s not how Australian contract law works.
The Contract Recipe
A binding contract needs four ingredients: an offer, acceptance, consideration (exchanging value) and an intention to be legally bound. What’s not included? Ink.
A signature is one way of showing the parties meant to be bound and it’s a very convincing indication, which is why it remains best practice. But it’s not the only way. Courts look at the full picture: the language used, the conduct of the parties, the surrounding circumstances. A signature can be compelling evidence of intention, but it is not a substitute for it. That cuts both ways. An unsigned agreement can still be enforceable if everything else points to the parties having struck a deal. And a signed document won’t necessarily lock things in if other conditions remain outstanding or the terms themselves are uncertain. But it’s not the only way and its absence doesn’t automatically mean there’s no deal. Equally, its presence doesn’t mean the deal is locked in either.
The case Australian lawyers reach for in this instance is Masters v Cameron. Here, the High Court was dealing with a familiar scenario: the parties had agreed on terms, but there was also talk of a more formal document to follow. The question was whether the deal was already done, or whether everyone was just warming up for the “real” contract.
When Signatures Matter, and Don’t Matter
The Court sorted these situations into three categories, which illustrate common contractual scenarios:
- “We’re bound now, and the formal document is just a record of it.”
Here, the parties have already struck their deal. The formal contract which will be signed later is just meant to tidy things up on paper. It is a formality, not a precondition. The result is that the agreement is enforceable straight away, signed document or not.
If the conduct of both parties aligns with the terms of the deal even having not signed anything yet, that contract will be enforced because of the intention evinced on both ends.
- “We’re bound now, but we won’t actually do anything until the formal document is signed.”
The terms of the deal have been finalised and is enforceable but performance (paying money, handing over goods etc.) is conditional on the formal document being executed. There’s a binding contract, and the parties are required to execute the formal document to give effect to the deal.
- “We don’t intend to be bound at all until the formal document is signed.”
In an instance such as this, the parties have only agreed in principle. Until that formal document is signed, there’s no contract and either side can walk away, no matter how detailed the email chain or how many times someone has said “deal”.
The difference between these categories comes down to the parties’ intention, worked out from the surrounding facts, the language used, the conduct of the parties and so on.
Does an Email Signature Count?
Then what of a typed name at the bottom of an email?
The good news (or bad news, depending on which side of the deal you’re on) is that a signature doesn’t have to be handwritten to do the job. An electronic signature counts provided all parties agreed to the electronic signing, the method used identifies the signatory and their intention in respect of the document and is as reliable as appropriate in the circumstances.
Just like a handwritten signature, it comes back to the full picture. An electronic signature might signal agreement to be bound, or it might just be how the sender ends every email. Automatically generated signature blocks tend to carry less weight for this reason – they’re present regardless of intention.
Take a contract formed purely through email with no attachments. An automatically generated signature block won’t do the heavy lifting here; it tells you very little about intention. An e-signature needs to evidence an intention to approve what’s being communicated, not just sign off on a Monday afternoon. That said, if the email containing the auto-signature also carried a clear statement of acceptance, the picture shifts. It’s all about context.
Why This Matters for Your Business
If you’ve ever:
- Sent a letter of intent or heads of agreement and assumed it was non-binding by default;
- Started performing under a deal while “the lawyers finalise the paperwork”; or
- Assumed an unsigned draft contract sitting in your inbox carries no legal weight
…then this is directly relevant to you. Depending on how things were worded and how everyone behaved you could already be bound, or you could be free to walk away.
In short: Signatures matter, but they’re not everything. They’re strong evidence of intention, and for some types of contracts (property transactions) they’re a legal requirement, not just good practice. But for many commercial agreements, the absence of a signature doesn’t automatically save you from being bound.
Quick Tips:
- If you’re opting for a ‘digital signature’ route, it’s worth clarifying with the other party what that looks like. A Docusign link lands very differently to a typed name at the bottom of an email.
- Already acting like the deal is done? Make sure your paper/digital trail reflects that. Make it clear to the other side “we consider this binding and the formal document is a formality”.
- If you’re not ready to commit, pop in a “subject to contract” as early and as consistently as you can.
And after all that, if you’re still in doubt about whether you’ve already committed or whether you can still back out – get in touch with us. It’s the kind of question worth asking a lawyer before you find out the answer in a dispute.
Watch out for the inner-Melbourne Congestion Levy – residential owners – Jack Nevile
Many clients are being caught unawares by the Congestion Levy. The Levy also applies to businesses, with many commercial landlords being caught out as well, however this article will only cover residential property.
Owners of carparks in inner Melbourne used for non-residential purposes (i.e. commuting) are liable for a Congestion Levy, payable to the state government.
The levy is currently $3,030 in the CBD plus some nearby areas, and $2,150 in inner-ring Melbourne (Carlton, Fitzroy, Richmond, South Yarra, South Melbourne, parts of Brunswick & St Kilda etc.)
The most common scenarios we’ve seen are:
- Owners of a parking space in the CBD who keep it for personal use, but don’t live in the building;
- Owners who rent out their private parking space to third parties on websites such as ParkHound etc.; or
- Owners whose tenants lease out a spare parking space to third parties on websites such as ParkHound etc.
The last scenario can prove a nightmare for landlords who are caught unawares when the tenant has been subletting a parking space to a commuter, and the SRO has found out. Rental parking websites are public, and it’s safe to assume the State Revenue Office scrolls them every now and again.
The landlord can be left with a hefty bill, even in scenarios where the tenant has vacated and the bond has been refunded. If the tenant was for example an international student, pursuing them for recovery of the debt might not be possible.
If you lease your parking space to a commuter, you must factor in the cost of the levy when doing so.
If you’re a residential landlord in the Congestion Levy area and your property include a carspace, you must consider the possibility of the Tenant subletting that parking space and ensure it is forbidden in the Lease.
If you don’t use your carpark, and it’s separately titled, consider selling it to someone who will, or leasing it to someone in the building who will only use it for residential purposes.
Property update – May 2026 Jack Nevile
Interest rates marching higher again, a Straight that apparently opens every Monday morning (US market time) and closes 4pm Friday (US market time), and jitters about negative gearing and CGT changes. You can get better tea-reading from others on those topics, so I won’t cover them here.
From 1 July 2026, investors will pay double the existing ESVF fixed charge on their investment properties, in line with commercial properties. This will come to approx. $300 per property, depending on the Minister’s determination. Principle places of residence will only pay about $150 of the fixed charge. All properties, PPRs and investments alike, will pay the floating rate based on their market value. See the State Revenue Office’s website here to calculate yours. Or just wait until later this year when you receive your rates notice.
More people have approached me with mind-boggling tax assessments due to the Vacant Residential Land Tax – I recently saw a bill for $65,000. Please, if you have a vacant house, put a friend or family in there, or rent it out on the market. Don’t leave it too late. You need it occupied 6 months of the year, so if your property has been empty all year, rectify that ASAP before 30 June.
Renters have been given a win recently, with notice periods for rent increases and vacating extended to 90 days, and no-fault evictions abolished. Rental applications must now used the prescribed form, and rental application apps can no longer charge for their ‘services’. Further changes are in the pipeline, including making it more difficult to claim a bond, and increasing the minimum standards some more.
While good for renters, I predict the changes from the last few years will mean it’s rare to see rundown houses in desirable locations up for rent – houses in desirable suburbs will likely be sold as they age and become too expensive to bring up to standard. I expect the rental market will gradually shift to apartments, which tend to be modern and already compliant with the standards. The effects on the Australian house party scene remain to be seen.
That said, we are not providing financial or tax advice. However, if you need legal advice, we’re the right people for you.
Disclaimer: This publication contains comments of a general and introductory nature only and is provided as an information service. It is not intended to be relied upon as, nor is it a substitute for specific professional legal advice. You should always speak to us and obtain legal advice before taking any action relating to matters raised in this publication.